Customer Statement of Account: Reconcile the Balance Before Collections
Prepare a customer statement that reconciles invoices, payments, credits, due dates, disputes, and the next billing action before collection escalation.
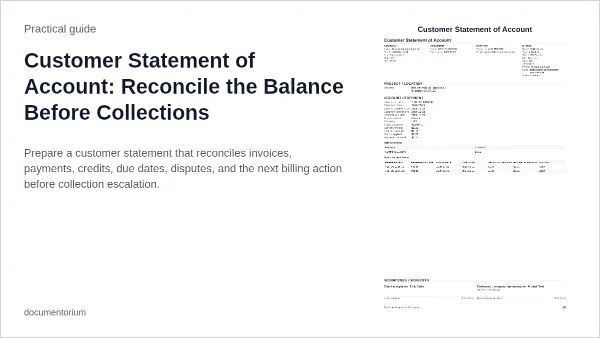
Example: A property manager receives a demand for $1,400 and says a $600 check was already sent. The shop's ledger shows that payment, but the statement does not identify where it was applied. A payment chase becomes an argument about records.
A statement of account summarizes a customer's transactions and balance over a defined period. Use Documentorium's customer statement of account template to show invoice references, payments, credits, and the remaining amount. Keep individual invoices and receipts available so the customer can trace a discrepancy rather than receive another unexplained bill.
Reconcile the ledger before sending it
Confirm the correct customer, legal payer, billing contact, account number, addresses or jobs, statement date, and period. Compare source invoices with settled payments, refunds, credits, deposits, and any unapplied money.
The SBA's financial-management guidance identifies accounts receivable and bank reconciliation among the functions a business needs to manage. Do that reconciliation before turning a ledger export into a customer demand.
Use the statement of account with the underlying invoices and receipts. For each adjustment, preserve the amount, date, reason, authorization, and affected invoice.
IRS Publication 583, December 2024, explains the supporting-document role of transaction records. Keep the statement tied to those sources; it does not replace the invoice detail or determine tax treatment by itself.
Show enough detail to locate the disagreement
A short running ledger is often sufficient:
| Illustrative activity | Charge | Payment or credit | Running balance |
|---|---|---|---|
| Opening balance, with prior open-item detail | — | — | $1,200 |
| INV-1142, approved service at the listed address | $850 | — | $2,050 |
| Receipt R-882, check applied to INV-1099 | — | $600 | $1,450 |
| Credit CM-22 applied to INV-1142 | — | $50 | $1,400 |
Identify dates and references on the actual statement. Do not count a previously included invoice again as a new charge or add a deposit twice. If a payment is unallocated, show that status and resolve its application using the agreement and applicable rules.
For a disputed service line, retain the work order, service report, and relevant approval. A statement total cannot fill a gap in the underlying work record.
Age invoices from their actual due dates
Separate the total open balance from the amount currently due. Show due dates and consistently defined aging buckets, such as current, 1–30 days past due, 31–60, and older. Those are illustrative reporting bands, not legal collection periods.
A new statement date should not silently reset an old invoice's due date or make a future milestone payable early. Identify disputed amounts, retainage, pending credits, or other conditions separately rather than calling every open item delinquent.
For progress billing, preserve the accepted milestone and completion conditions. For added work, reconcile the approved change order to the billed amount. The change-order guide explains that approval record; the written-quote guide helps establish the original price.
Only include late charges after checking their accepted basis and applicable law. State the calculation and affected principal. The statement should not introduce a new fee as pressure to pay.
Give the customer a clear response path
Use a practical message:
Please review the activity and payment application shown. If your records differ, send the invoice number, payment reference, job address, or credit you believe is missing. Contact billing at the listed address for copies or reconciliation. Please pay amounts due under the applicable terms.
A requested reply date is an administrative follow-up point, not an automatic waiver of the customer's rights. Do not describe silence as acceptance of every line.
Give the payee, permitted payment methods, remittance destination, and references to include. After payment, issue a receipt showing application across invoices where needed and update the remaining balance.
Keep billing and regulated collection duties distinct
Before escalation, classify the account and sender. Regulation F's definitions, 12 CFR 1006.2, distinguish covered consumer debt, creditors, and debt collectors, with conditions and exceptions. State collection and consumer-protection laws can have different coverage. Calling a document a “statement” does not decide those questions.
For a covered debt collector, a routine ledger does not replace required validation information under 12 CFR 1006.34. Keep that process, applicable dispute rights, and deadlines intact.
Send a supported past-due notice only after reconciling the account and reviewing the appropriate next step. Do not threaten a lien, lawsuit, credit report, suspension, or fee without its actual legal and contractual basis. Track any statutory preservation deadlines separately from ordinary billing correspondence.
Save the issued statement and customer response. Verify recipients and restrict sensitive payment details. The FTC's business data-security guide recommends retaining needed information, limiting access, and secure disposal when the need ends.
Common questions
Is a statement another invoice?
No. It summarizes account activity and balances while pointing to the invoices, receipts, and adjustments that support them.
What if the customer disputes one line?
Record the dispute, review the source evidence, and reconcile any correction. Identify other amounts and their due status accurately rather than obscuring the challenged line.
Does sending a statement preserve lien or collection rights?
Do not assume so. A billing summary does not replace a required notice, filing, or other statutory step.
Sources reviewed October 18, 2026.
Useful documents for this job
Related blog posts
- Milestone Billing Schedules for Multi-Week Construction Jobs
- Written Quotes for Contractors: Scope, Price, and Approval Records
- General Service Work Orders for Multi-Trade Shops
- Chargeback Defense Packets for Service Work: What to Include
- Pay-When-Paid vs. Pay-If-Paid: Timing, Risk, and State Rules
- Stopping Work for Nonpayment: The Notice Sequence Before You Pull Off
- Slow-Pay Packet for Small GCs: What to Include Before You Escalate
- Small Claims Court vs. Arbitration: Choosing a Payment Dispute Process
- Material Takeoff Reconciliation: Field Use, Returns, and Variances
- Schedule Change Notices: Dates, Causes, and Approval Records
- Moving Estimates: Bills of Lading, Valuation, and Tariffs
- How to Write Late-Fee Terms for Quotes and Service Contracts